StreamBank has launched a structured finance proposition offering loans of up to £5 million over terms of up to five years, targeting high-net-worth borrowers whose repayment plans extend beyond conventional bridging timescales.
The new product is designed for borrowers who have a credible exit strategy but require longer to realise funds from property transactions, business disposals or other assets.
Positioned between traditional bridging loans and conventional mortgages, the facility combines individual underwriting with repayment terms ranging from 12 to 60 months.
StreamBank said the proposition recognises that complex transactions involving high-value assets can take considerably longer than the 12 months typically associated with bridging finance.
LOAN TERMS AND ELIGIBILITY
Facilities are available from £350,000 to £5 million, although loans exceeding £3 million require additional approval. The maximum loan-to-value (LTV) is 65%, with lower limits applying to larger advances.
Lending is secured against residential property in England, Wales and Scotland and can be used for purchases, refinancing and evidenced capital-raising requirements.
Eligibility is restricted to borrowers meeting specific wealth criteria. At least one applicant must independently earn a minimum annual net income of £300,000 or hold net assets of £3 million or more, excluding their main residence.
Borrowers can choose between fully rolled-up, part-serviced and fully serviced interest arrangements, providing flexibility according to their income and cash flow.
Potential repayment strategies include the sale of higher-value residential properties, business disposals, share realisations and the completion of development projects.
LONGER REPAYMENT TIMESCALES
Richard Armstrong, chief commercial officer at StreamBank, says: “The reality is that high value property and business transactions don’t always adhere to a 12-month timeline.
“A borrower can have a perfectly credible exit strategy, but achieving the right commercial outcome can sometimes take longer than originally anticipated.
“A property may be attracting genuine interest, or a business or asset sale may be progressing well, but transactions of this nature are often complex and completion dates can move. Taking longer doesn’t necessarily make the exit less credible.
“In some circumstances, allowing more time can actually support a better and more commercially sensible outcome.”
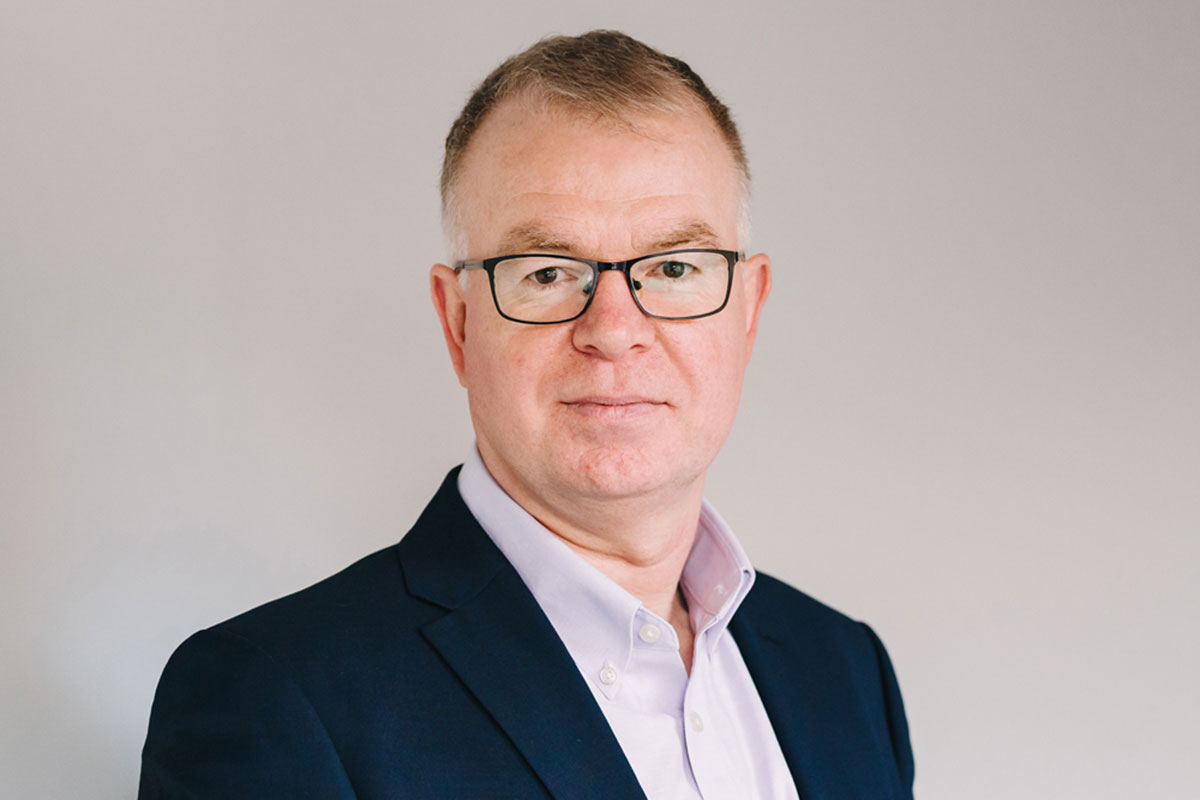
Armstrong (pictured) says the lender would continue to assess the strength of borrowers’ repayment strategies rather than rely solely on their financial resources.
He adds: “We still apply robust underwriting, but we also recognise that substantial wealth does not necessarily mean immediate liquidity.
“The important thing for us is that the term of the finance reflects a realistic route to repayment, rather than assuming every credible exit can or should be delivered within 12 months.”