Property refurbishments, extensions and conversions can leave existing rebuild cost assessments out of date, potentially resulting in inadequate insurance cover, according to RebuildCostASSESSMENT.
The insurance valuations specialist says significant alterations such as extensions, loft conversions, roof changes or changes to internal layouts can affect the cost of reinstating a property.
However, less substantial refurbishment work can also have an impact, particularly where improvements increase the specification of a building.
New kitchens and bathrooms, higher-specification finishes, upgraded heating systems and fixed air-conditioning are among the improvements that could alter a property’s rebuild cost.
CONVERSIONS CAN CHANGE REINSTATEMENT COSTS
Changes in use can also trigger the need for a reassessment.
Converting an office into residential accommodation, for example, can substantially change the building and its reinstatement requirements.
A new occupier making alterations or installing fixed equipment could similarly mean that an existing rebuild cost assessment no longer accurately reflects the property.
RebuildCostASSESSMENT says its research earlier this year found 67% of UK properties were underinsured and 25% were overinsured, with just 8% accurately insured.
The company recommends arranging a new rebuild cost assessment every three years, even where no significant alterations have taken place.
‘ASSESSMENT MAY NO LONGER REFLECT THE BUILDING’
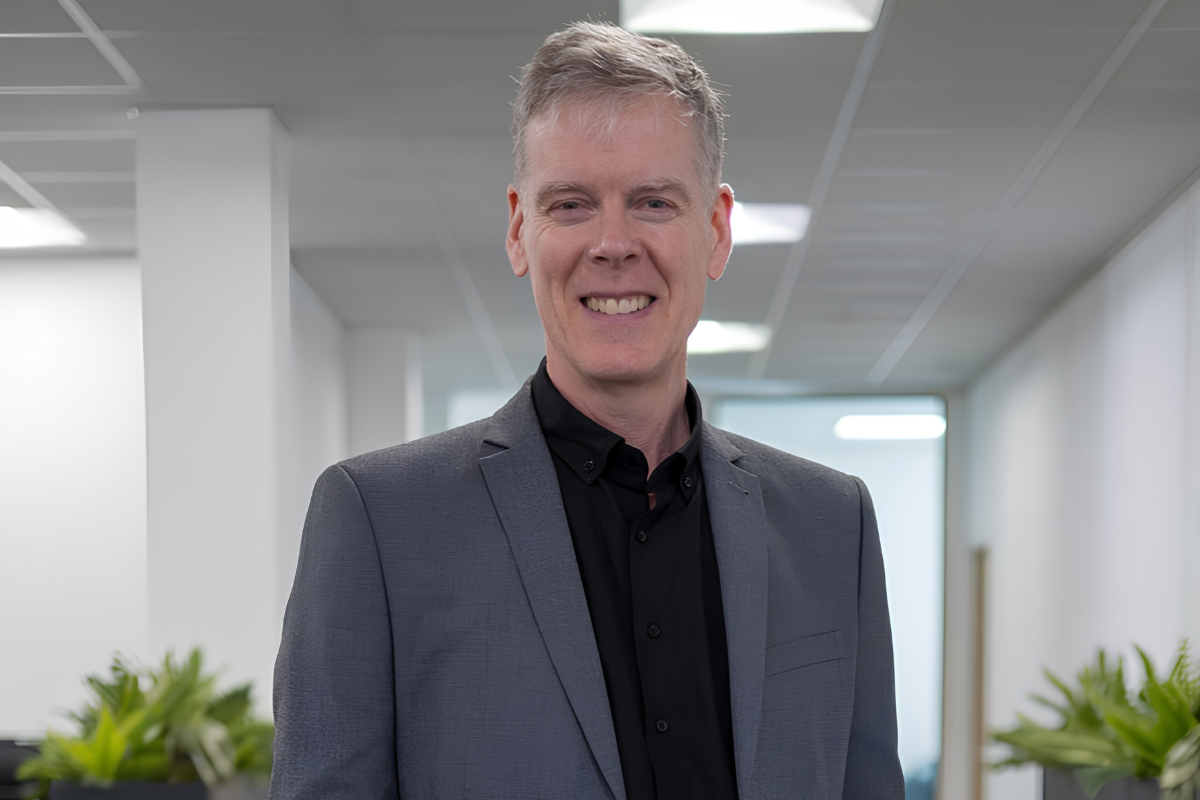
Johnny Thomson (main picture), head of strategic planning at RebuildCostASSESSMENT, says: “One of the most obvious reasons to review the property’s rebuild cost is if significant alterations have been made.
“These could include adding an extension, converting a loft, changing the roof or altering the internal layout. It’s changes like these that could affect the cost of reinstating a property and invalidate the previous rebuild cost assessment, which may no longer accurately reflect the building as it stands today.”
He adds: “The key question to ask is: has the property changed significantly, or is the existing assessment getting older? If there have been changes, it could be time for a new rebuild cost assessment.
“The most important thing is to stay on the ball and regularly check the age of the last assessment and to consider carefully whether any recent changes made to the property could affect the rebuild cost, in the event of a claim. The best advice is don’t get caught short!”