The collapse of Market Financial Solutions (MFS) has prompted a tightening of funding appetite across specialist lending, with smaller lenders and new entrants potentially facing the greatest pressure, industry figures have warned.
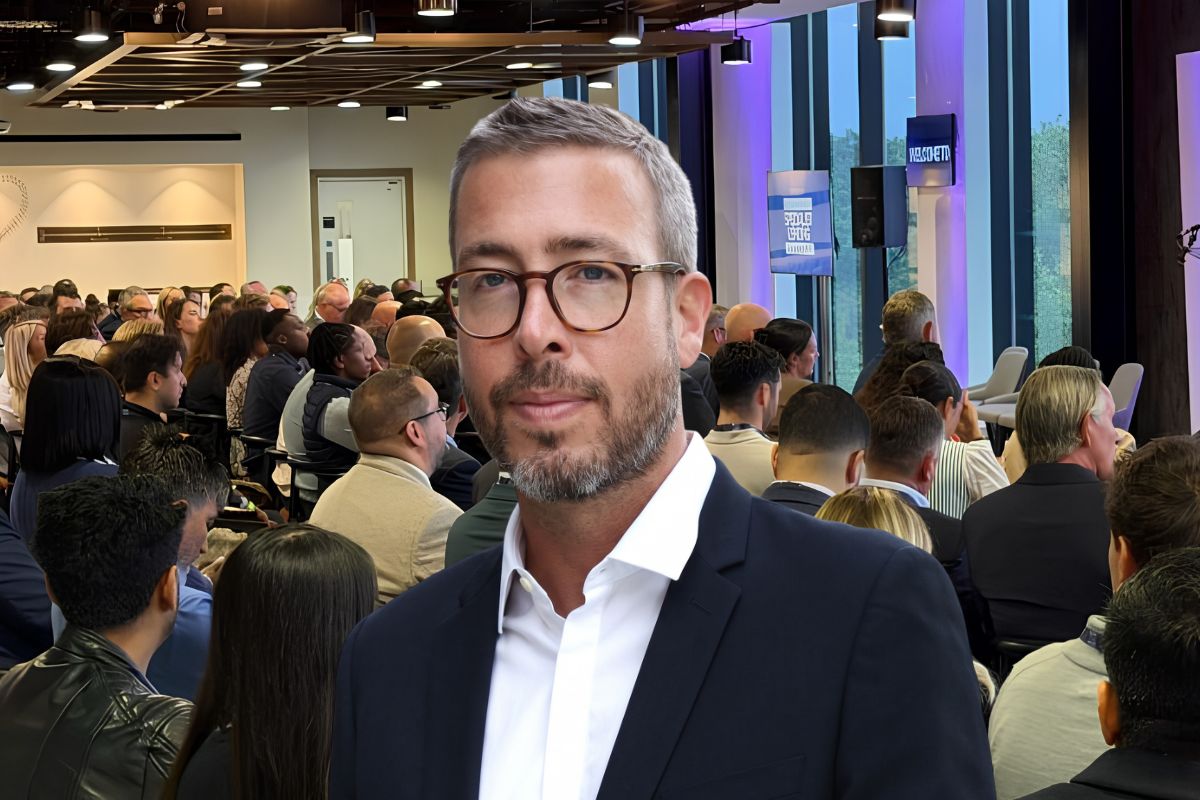
Speaking during a lender panel at the Brightstar Specialist Lending Expo 2026 last week, MT Finance CEO Joshua Elash (main picture, inset) said he did not believe the issues surrounding MFS pointed to a systemic problem among specialist lenders.
Instead, he said the greater risk was the reaction of capital providers, with some major institutions either withdrawing or significantly reducing their appetite to fund specialist lenders.
The resulting tightening could make it more difficult for lenders without diversified funding arrangements to raise additional capital and potentially affect the terms available from existing funders.
‘TIGHTENING OF CREDIT APPETITE’
Elash says: “Is there a systemic risk that this alleged specific type of activity is occurring or is prevalent? No, I don’t believe that there is.
“Where does the real risk lie off the back of this? It’s the impact it has on the capital markets, and what we’ve seen is that there’s a tightening of credit appetite.”
He warns that lenders with less diversified funding structures could be particularly exposed.
“Smaller lenders, or even medium-sized lenders who don’t have diversified capital stacks, are going to now really struggle to expand their capital stacks.”
Elash says lenders dependent on a single funder could also face changing requirements, including pressure to reduce loan-to-values.
“It’s also going to be harder for new entrants to come and raise capital funding from the capital markets because people are scared,” he adds.
LENDERS TIGHTEN SYSTEMS
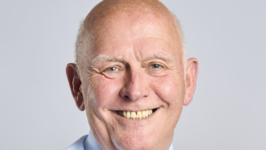
Keystone Property Finance CEO David Whittaker says the events surrounding MFS have also resulted in lenders strengthening systems and processes.
He says greater information sharing and checks across different funding arrangements are now necessary, with lenders having to demonstrate stronger oversight of assets and data.
Whittaker says: “If you’re an originating lender with your own balance sheet or dependent on other institutional counterparties, you’ve got to tighten up your systems.”
However, he warns that additional controls ultimately come with a cost.
“There’s a cost for all this, and the consumer, be it a buy-to-let landlord or the consumer, ultimately always pays,” he says.