Bellway is directing a greater proportion of its land investment towards northern England as the housebuilder responds to tighter development margins and continued pressure on buyer demand.
The group contracted to purchase 8,578 plots during the year to 31 July 2026, up from 8,120 the previous year, despite reducing its total contracted land expenditure from £566.8m to £505.1m.
The acquisitions were spread across 35 sites, compared with 51 a year earlier, reflecting a more selective approach to land investment.
Some 78% of newly contracted plots were located in Bellway’s northern divisions, up from 66% in 2025.
The figures highlight the importance of land acquisition costs and regional development economics as housebuilders seek to protect returns in a challenging market.
LAND INVESTMENT
Bellway ended July with a total land bank of 94,666 plots, including 45,992 owned and controlled plots.
Its strategic land bank remained broadly unchanged at approximately 48,000 plots, providing a pipeline of future development opportunities.
The housebuilder says it will continue allocating capital selectively while maintaining a strong balance sheet and prioritising operational efficiency.
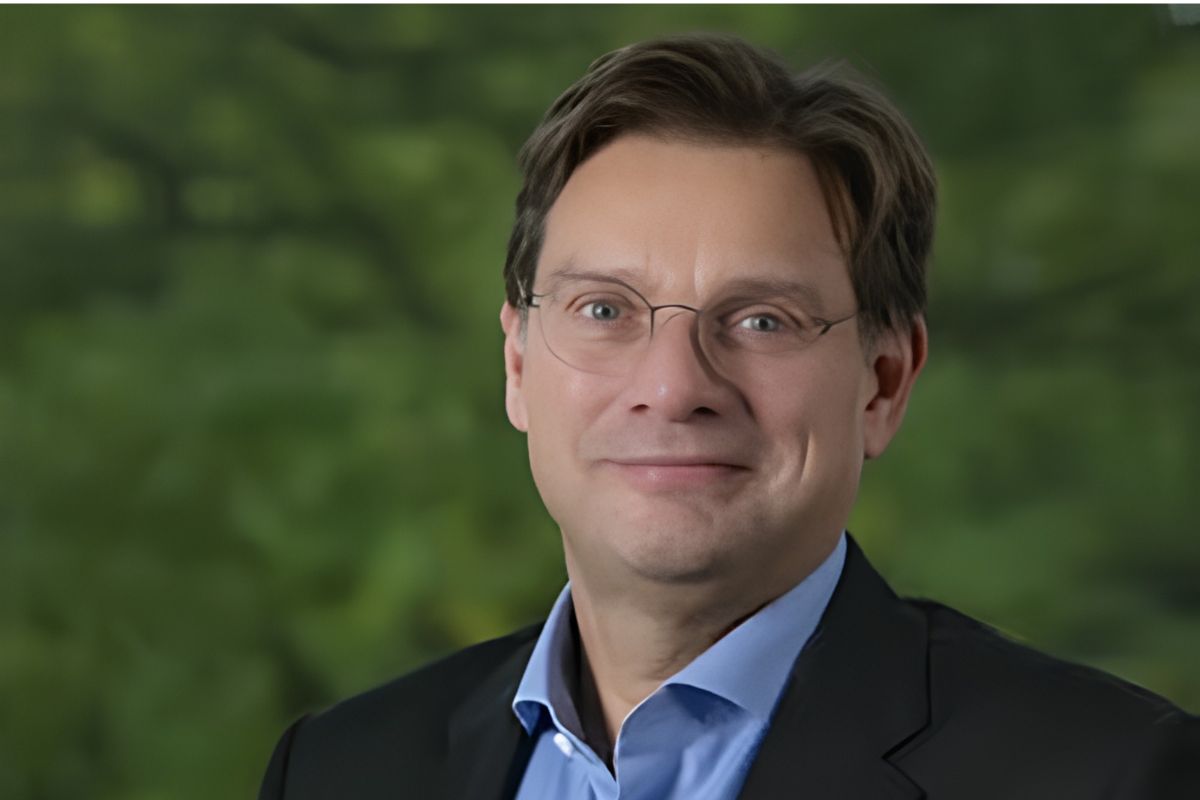
Jason Honeyman (main picture), chief executive of Bellway, says: “Against a backdrop of near-term economic uncertainty, our priorities remain clear: allocating capital with discipline, maintaining a strong balance sheet with low gearing and investing selectively in land to support future growth.”
DEVELOPMENT MARGINS
Bellway’s underlying operating margin fell from 10.9% to 10.1% during the financial year, despite completions increasing 10.8% to 9,695 homes.
The group expects margins to come under further pressure in FY27 as build cost inflation, higher sales incentives and a greater proportion of bulk sales outweigh operational improvements.
Sales incentives increased from an average of 4.1% to approximately 5%, reflecting continued affordability pressures among purchasers.
Bellway is forecasting between 9,000 and 9,400 completions in FY27, below the 9,695 delivered during the latest financial year.
Its private reservation rate, excluding bulk sales, fell to 0.45 per outlet per week in the nine weeks from 1 August, compared with 0.48 a year earlier.
For smaller developers and specialist development finance lenders, the results provide a wider indication of the pressures affecting scheme viability, particularly where construction costs, land values and achievable selling prices are tightly balanced.
Bellway says its selective land investment, improved capital efficiency and accelerated completion of lower-margin developments should support stronger margins and returns beyond FY27.