Construction remains the sector with the highest number of company insolvencies in England and Wales, with 3,866 businesses entering insolvency in the 12 months to August.
The sector accounted for 17% of all insolvencies where an industry was recorded, ahead of wholesale and retail at 15% and accommodation and food services at 14%.
There were 294 construction insolvencies during August, marginally higher than the 292 recorded in August 2025.
However, the longer-term picture shows some improvement, with construction insolvencies over the latest 12 months 2% lower than during the preceding 12-month period.
HOUSING ACTIVITY UNDER PRESSURE
The figures come amid continued pressure on construction and housebuilding activity.
Latest Office for National Statistics figures show construction output fell by 0.5% in the three months to July, with both new work and repair and maintenance declining.
Although total construction output edged 0.1% higher during July itself, the increase came entirely from repair and maintenance. New work fell 0.4%, with private housing new work recording a 4.9% monthly decline.
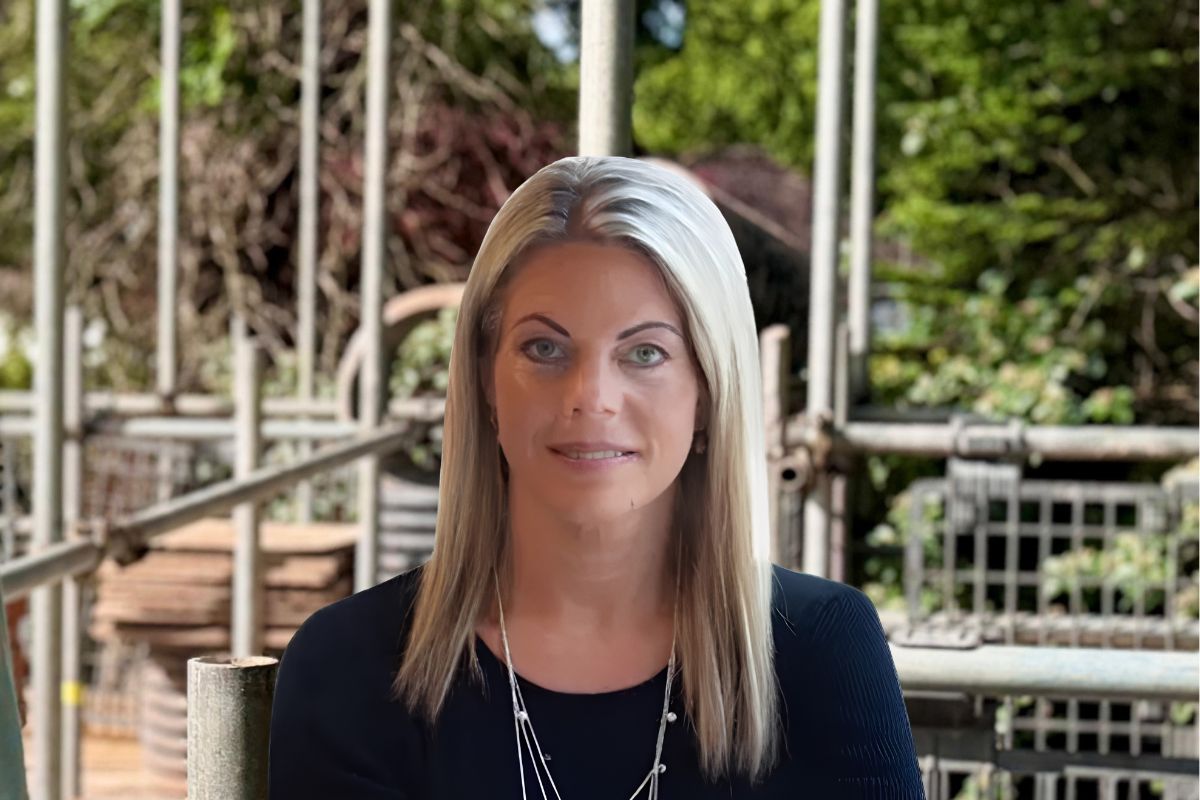
Kelly Boorman (main picture, inset), head of construction at RSM UK, says uncertainty over future pipelines, financing costs and wider economic conditions continue to weigh on the industry.
‘PRESSURE BUILDS THROUGHOUT THE SUPPLY CHAIN’
Boorman says: “Long-term uncertainty over future pipeline allocation and mobilisation, along with macro-economic conditions, is weighing heavily on the construction sector as rising inflation, energy price volatility and the potential for interest rate hikes later in the year fuels concerns around financing and funding. Many construction firms, particularly housebuilders, are restructuring to manage delivery and protect margins amid expectations of continuing economic challenges.
“There are signs of short-term market health, as businesses continue to deliver on secured pipelines. However, the long-term outlook faces uncertainty around when and where major infrastructure spend will be allocated.
“Housing volumes also remain challenged with private residential demand declining further and social housing funders seeing funding structure changes, and major developers are announcing cuts to their housebuilding targets. As concerns over demand and project viability ramp up, pressure builds throughout the supply chain around activity volumes and debt affordability and servicing.
“Unfortunately, as the sector braces for winter weather, further uncertainty over policy and high energy prices pushing inflation to over 4%, we could see the upward trend in sector insolvencies continue in the coming months.
“Businesses continue to proactively restructure to boost resilience and relieve pressure on margins, but greater clarity around major project spend and timelines, along with access to affordable debt, will be crucial to enable businesses to plan and adequately scale, securing long-term viability.”